 rumaruma
Should You Take a Loan for Home Renovation in Malaysia?
When borrowing for a renovation makes sense, which loan costs the least, and the numbers to check before you sign anything.
On this page
The keys are in your hand, the ID’s quotation says RM85,000, and your savings say RM40,000. Somewhere between those two numbers sits the question every second Malaysian homeowner ends up asking: do you borrow the rest, or wait?
A loan for home renovation in Malaysia isn’t automatically a bad idea, and it isn’t free money either. Borrowing works for some situations and quietly backfires in others. Which loan you take can also move your total interest by RM10,000 or more on the same amount. This guide covers when borrowing is worth it, what each option really costs, and a rule change coming in January 2027 that’s worth knowing about.
When Borrowing for a Renovation Makes Sense
The short version: borrow to make the home work, not to make it impressive. A loan makes most sense when the work can’t sensibly wait, or when waiting would cost more than the interest.
- The unit isn’t liveable yet — a new key-collection unit with no kitchen, no wardrobes and no water heater. You’re paying rent and an instalment at the same time, so every month of delay costs real money.
- The work fixes a defect — a leaking roof before monsoon season, failed bathroom waterproofing seeping into the unit below, or 30-year-old wiring in a terrace house. Delaying these makes the repair bigger.
- You’re doing the messy work once — hacking, rewiring and re-plumbing before you move in is far cheaper and less disruptive than doing it around your furniture three years later.
- The renovation adds lasting value — a properly done kitchen or bathroom in a home you plan to stay in for 10+ years, or a rental unit where the upgrade lifts the monthly rent.
When You Should Probably Wait
Borrowing gets harder to justify when the money goes into things that date quickly or could be added later.
- Feature walls, decorative lighting, loose furniture and styling — none of these need doing on day one, and paying them off over seven years means you’re still paying long after you’ve grown tired of them.
- Upgrades to keep up with a friend’s or influencer’s renovation — if the loan is what makes the scope possible, the scope is probably too big.
- Any renovation where the monthly repayment leaves no emergency buffer — a job loss or medical bill with a fresh renovation loan on top is how short-term debt turns long-term.
A useful test: if you’d still want this item in five years, financing it can make sense. If you’re not sure, save for it.
Your Options for Renovation Financing in Malaysia
There are five main ways Malaysians pay for a renovation that savings can’t fully cover. They differ a lot in cost, speed and risk.
| Option | How it works | Typical cost | Speed | Main risk |
|---|---|---|---|---|
| Mortgage top-up or refinance | Borrow against your home’s equity, repaid with your home loan | Close to home loan rates (reducing balance) | Slow — weeks for valuation and documents | Your home is the collateral; long tenure means more total interest |
| Bank renovation loan | A dedicated renovation facility, often tied to your mortgage, paid out against contractor invoices | Between mortgage and personal loan rates | Moderate | Staged release can clash with contractor payment terms |
| Personal loan | Unsecured loan, lump sum to your account | Highest of the bank options — advertised as a flat rate | Fast — days | Effective rate is much higher than the advertised rate |
| EPF Akaun Fleksibel | Withdraw from your own flexible EPF account | No interest, but you lose future dividends | Fast | Shrinks your retirement savings |
| Credit card instalment / contractor financing | 0% or low-rate instalments on specific purchases | Low if paid on schedule; very high if you miss payments | Instant | Card interest of up to 15–18% p.a. if anything slips |
Interest rates change often and depend on your income, credit record and existing loans, so check current offers directly with the bank. Bank Negara’s Overnight Policy Rate (OPR) has been held at 2.75% through 2026, which is why home loan rates have stayed fairly stable this year.
Mortgage Top-Up or Refinancing
If your home has risen in value or you’ve paid down a good part of your loan, you may be able to borrow against that equity. Because the loan is secured on your property, the rate sits close to your home loan rate and is calculated on a reducing balance.
The catch is speed and paperwork. Expect a valuation, legal documents and fees, and a few weeks before the money is available. Refinancing to a new bank can also bring lock-in penalties from your old one, so ask about these before you start.
Bank Renovation Loans
Several Malaysian banks offer renovation-specific products. Some are bundled with your mortgage — Maybank’s Home + Reno Loan and RHB’s My1 Renovation Loan are two long-running examples — and in September 2026 RHB launched a facility with The Makeover Guys that finances the purchase and renovation together. These usually pay the contractor directly, in stages, against invoices.
That staged release protects you from paying for work that hasn’t been done, which is useful. It also means your contractor has to accept the bank’s payment timing, so confirm this before you sign the renovation contract.
Personal Loans
A personal loan is the quickest option. Approval can take a few days, and the money lands in your account to spend as you need. That convenience costs more than it first appears to.
Most Malaysian personal loans are still advertised at a flat rate, which charges interest on the full amount for the whole tenure, even as you pay it down. A 6% flat rate sounds cheaper than a 4.2% home loan rate on the face of it, but the real comparison looks like this.
What a RM50,000 Renovation Loan Actually Costs
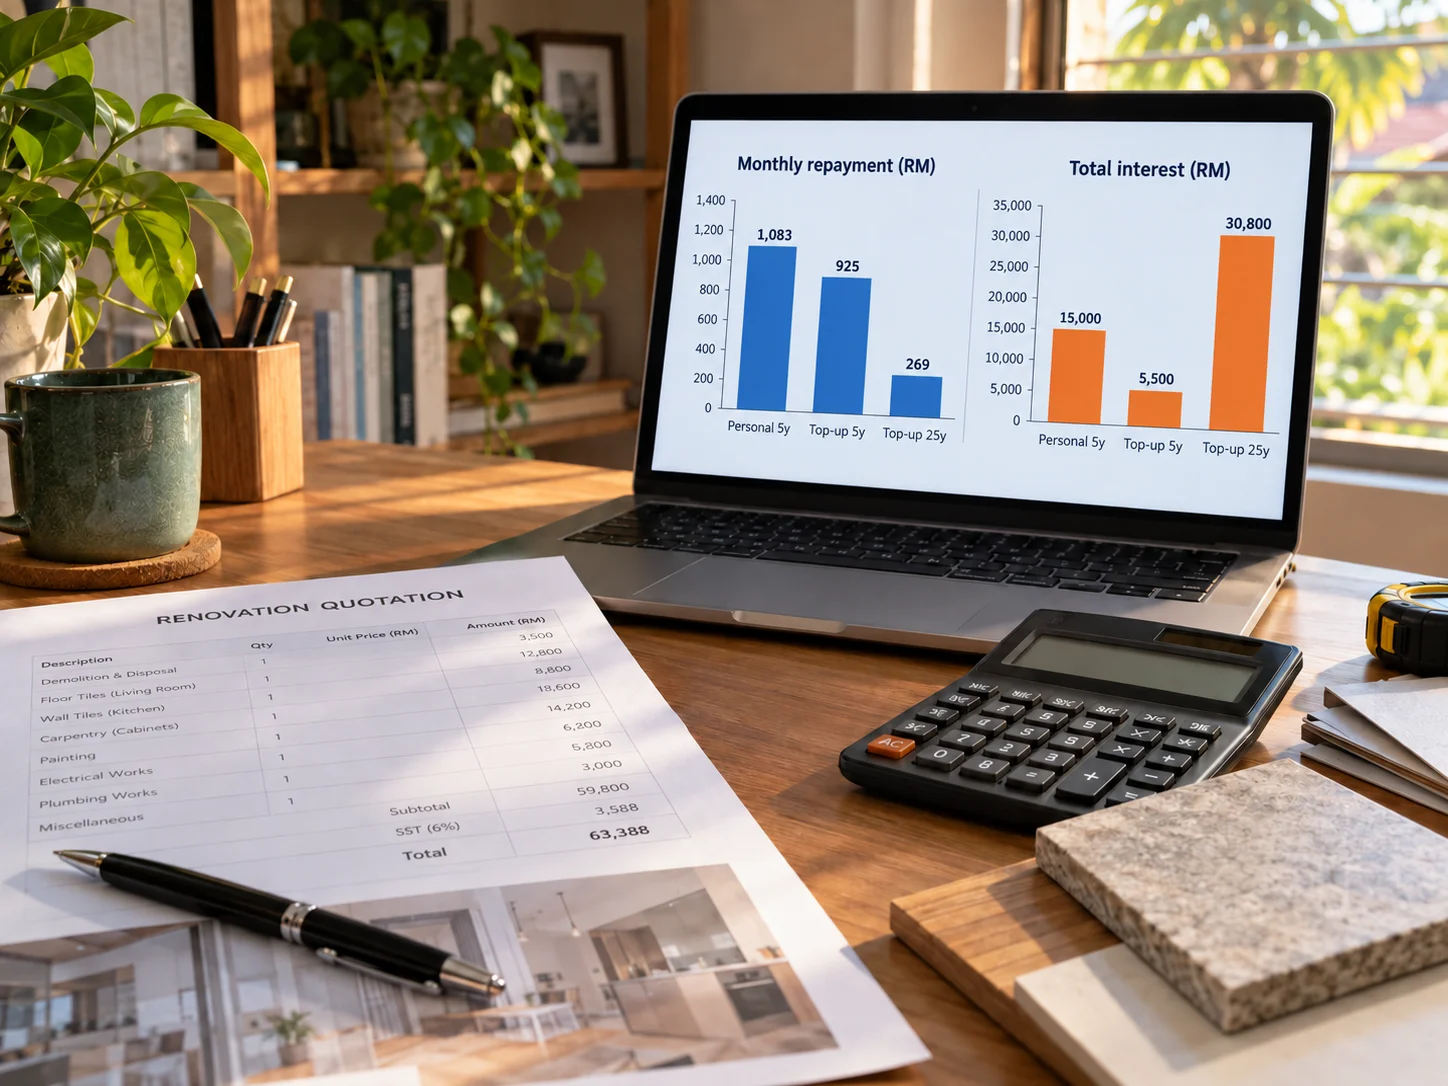
Here is the same RM50,000 borrowed three ways. The figures are worked examples to show how the maths behaves, not offers from any specific bank.
| Personal loan, 6% flat, 5 years | Mortgage top-up, 4.2% reducing, 5 years | Mortgage top-up, 4.2% reducing, 25 years | |
|---|---|---|---|
| Monthly repayment | RM1,083 | RM925 | RM269 |
| Total interest paid | RM15,000 | RM5,500 | RM30,800 |
| Effective annual rate | ~10.8% | 4.2% | 4.2% |
Two things stand out. First, a 6% flat rate behaves like roughly 10.8% on a reducing balance, so it costs nearly three times as much interest as the top-up over the same five years. Second, stretching a top-up over 25 years makes the monthly figure look tiny, but you’d pay more total interest than with the personal loan.
So the cheapest option is usually a secured loan, repaid over a short tenure. If you top up your mortgage, ask whether you can pay the renovation portion off early without a penalty.
The January 2027 Rule Change
From 1 January 2027, Bank Negara Malaysia’s revised fair-treatment policy bans flat-rate pricing on new personal financing. Banks will have to calculate interest on the reducing balance and show the effective interest rate on every offer. The same policy also requires anyone borrowing more than RM100,000 in personal financing to complete a short financial education module first.
The ban covers new agreements only. A flat-rate loan you sign in late 2026 stays flat-rate for its full tenure. If you’re planning to borrow on a personal loan and the timing is flexible, waiting until 2027 makes offers easier to compare. If you need the money now, ask the bank for the effective rate in writing and compare that figure, not the advertised one.
How Much Can You Safely Borrow?
The bank will tell you how much it’s willing to lend. That’s not the same as what you can comfortably repay. Banks look at your debt service ratio (DSR) — your total monthly loan repayments as a share of your net income — and many will approve loans up to roughly 60–70% DSR depending on your income level. At that point, most households have very little left for anything else.
A safer personal ceiling is to keep all your loan repayments (home, car, PTPTN, personal and renovation) at or below about 40% of your take-home pay. Then check two more things:
- Your emergency fund stays intact — at least three to six months of expenses, untouched by the renovation.
- The renovation budget includes a contingency — 10–15% on top of the quotation. If you borrow the exact quoted amount, any variation order goes straight onto a credit card.
For the full method of building that ceiling from cash, borrowing and contingency, see our guide on how to set a realistic renovation budget. It’s also worth reading the hidden renovation costs Malaysian homeowners forget before you settle on a loan amount — JMB deposits, debris removal and M&E surprises add up fast.
Using EPF for Renovation: The Akaun Fleksibel Option
Since EPF restructured its accounts in May 2024, members under 55 have three accounts. Akaun Sejahtera (the old Account 2) only allows withdrawals for approved purposes such as buying or building a home, and renovation isn’t one of them. Akaun Fleksibel can be withdrawn for any reason, renovation included, through the KWSP i-Akaun app.
It’s interest-free, but it isn’t free. Every ringgit you take out stops earning EPF dividends, and compounding over 20–30 years makes that a bigger loss than it looks today. Akaun Fleksibel can sensibly cover a small gap, say the last RM5,000–10,000, so you avoid a personal loan. Using it to fund the whole renovation is harder to justify.
Cut the Loan Before You Sign It
The cheapest loan is the one you don’t take. Before applying, go back through the quotation and see how much of it can wait.
- Phase the scope — do the hacking, wiring, plumbing, waterproofing and kitchen now. Leave feature walls, decorative ceilings and loose furniture for when you’ve saved again.
- Negotiate line by line — an itemised quotation gives you room to adjust materials and specs without hurting the build quality. Our guide on how to negotiate renovation costs without compromising quality walks through it.
- Choose materials that last — spending a little more on things you’d otherwise replace in five years is a better use of borrowed money than decorative extras. A humidity-proof countertop or properly waterproofed bathroom pays for itself; a trendy pendant light usually doesn’t.
- Check real prices first — our 2026 renovation cost guide shows typical RM ranges by room and home type, so you know whether a quote is reasonable before you borrow to pay it.
Trimming RM15,000 of non-essential work from an RM85,000 quotation can turn a loan you’d struggle with into one you’d barely notice.
Before You Sign a Renovation Loan: Checklist
- Your quotation is itemised, and you’ve separated must-do work from nice-to-have
- You’ve added a 10–15% contingency to the amount you plan to borrow
- All your loan repayments together stay at or below about 40% of your take-home pay
- Your emergency fund is untouched
- You’ve compared the effective interest rate of every offer, not the flat rate
- You’ve asked your current bank about a mortgage top-up before applying for a personal loan
- You know the early settlement terms and any lock-in penalty
- Your contractor agrees to the bank’s payment schedule (for staged-release renovation loans)
- Your contractor is CIDB-registered and your JMB/MC renovation approval is in place before work starts
- If you’re taking a personal loan, you’ve considered whether waiting for the January 2027 rules is an option
The right loan, sized properly, can get you into a home that works on day one, with a kitchen you actually cook in and a bathroom that won’t leak into your neighbour’s ceiling. Borrow for the parts that make the house liveable, pay cash for the parts that make it special, and you’ll still enjoy the result long after the last instalment is paid.